

Interview: Nicolien Vrisou van Eck on EBN’s Fill Obligation for Underground Gas Storage
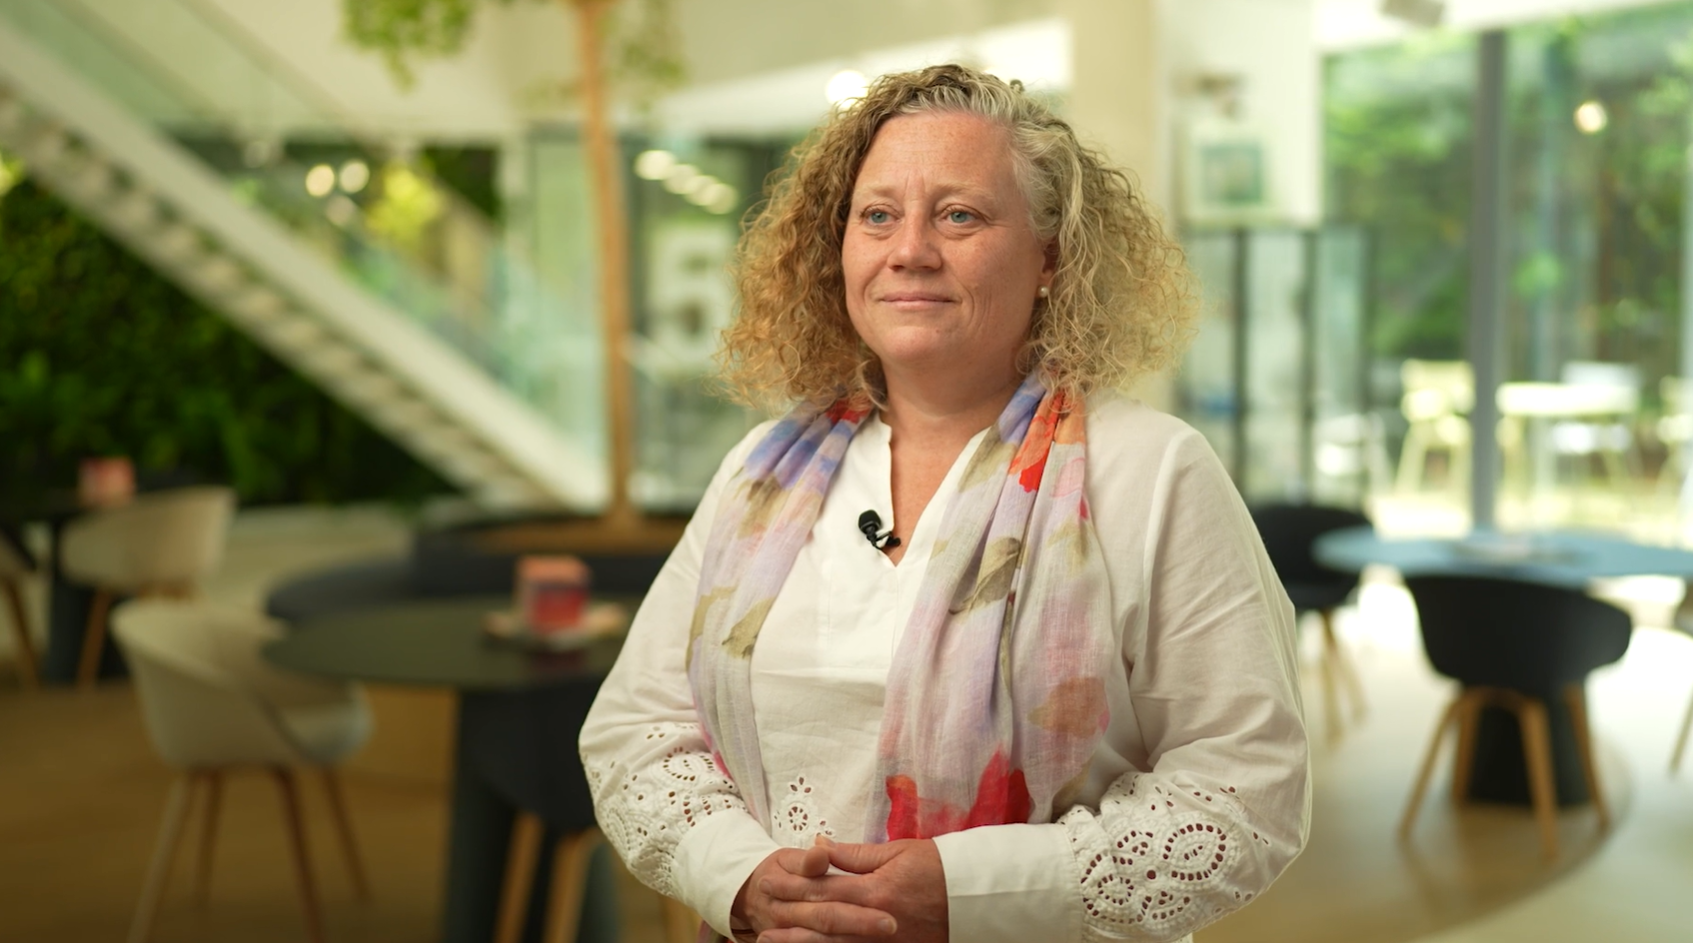
Developments in the international energy market and the changing geopolitical landscape have major implications for energy supply and the use of underground gas storage facilities. Following her contribution to the Technical Briefing to the House of Representatives on 13 May, Nicolien Vrisou van Eck, Director Gas Transition at EBN, explains in this interview the challenging circumstances under which EBN, as a public energy company, fulfils its fill obligation. At the same time, she stresses that a more structural approach and long-term policy framework are needed to safeguard energy security in the future.
What is the role of underground gas storage facilities since the closure of the Groningen gas field?
Since the closure of the Groningen gas field, the Netherlands no longer produces enough natural gas to meet domestic demand. Approximately three-quarters of Dutch gas consumption is imported. This makes us vulnerable if disruptions occur in supply chains. These may include geopolitical tensions, pipeline sabotage or issues with LNG deliveries. Gas storage facilities ensure that gas is physically available in the Netherlands and serve as our buffer for the winter season. During summer, gas consumption is lower and storage facilities are filled. During winter, these storage facilities are used to supply gas to the Netherlands.
What part of the storage capacity is EBN responsible for?
The Netherlands fills its gas storage facilities in accordance with European regulations. With 115 TWh stored in Dutch gas storage facilities, the country comfortably meets the European filling target of 74%. EBN has a fill obligation of 85 TWh for the PGI Alkmaar, Grijpskerk, Norg and Bergermeer storage facilities. The remaining 30 TWh is the responsibility of the market.
Bergermeer is the only storage facility that is commercially accessible to multiple parties simultaneously. EBN can use storage capacity in Bergermeer on an interruptible basis. Norg and Grijpskerk can each only be used by a single capacity holder. Until recently, that capacity holder was GasTerra, but the company will cease its activities at the end of 2026. For Norg, EBN now has a capacity agreement with NAM. A capacity auction for Grijpskerk is currently underway in line with the assignment issued by the Authority for Consumers and Markets (ACM).
For the Peak Gas Installation (PGI) in Alkmaar, representing 5 TWh, EBN has entered into a seven-year agreement. This volume is currently used as seasonal storage, but following the entry into force of the Energy Supply Crisis Act, it is likely to be designated as an emergency reserve. The implementation of this legislation has, however, been delayed.
Is filling the gas storage facilities economically viable?
At present, there is what is known as a negative spread, meaning that summer gas prices are higher than winter gas prices. As a result, storing gas is commercially unattractive. This raises the question of whether the market will realise its share of 30 TWh. Companies cannot be required to undertake loss-making activities. For EBN, purchasing gas at current prices is also not economically viable, which is why subsidy support has been made available for this activity. When filling gas storage facilities, we make every effort to minimise market distortions and limit the use of subsidies as much as possible. This requires careful timing and calibration of gas purchases and sales.
What about the €21.6 billion allocated to EBN that has received considerable attention?
Let me explain. The €21.6 billion consists of two components. First, there is a subsidy intended to cover the costs associated with the negative spread and storage operations. Naturally, we aim to keep these costs as low as possible. They amount to a maximum of €1 billion, although the final outcome depends heavily on market price developments.
In addition, there is a loan of more than €20 billion. This loan is repaid once the gas has been delivered. It is required because, in the event of rising prices, collateral must be posted to the seller of the gas. This enables the seller, if delivery does not take place for any reason, to purchase replacement gas at the prevailing higher market price. The loan therefore serves exclusively as risk coverage and will be repaid in full.
Will the Netherlands achieve the filling target of 74%?
That is difficult to predict. Filling activities are progressing, but at a slow pace, and market participants are filling little or no storage capacity. The negative spread is a key factor. If the spread turns positive, gas storage will once again become attractive for the market.
Gas price developments are influenced by geopolitical events, including the situation around the Strait of Hormuz. However, even if the Strait of Hormuz were reopened, that would not mean LNG becomes immediately available. There is a delay of at least three months before the first LNG cargoes could arrive. Combined with uncertainty around the outcome of ongoing negotiations, that would already take us well into the winter season.
Furthermore, Grijpskerk is not yet being filled because its capacity is still being auctioned. Another factor is that GasTerra handed back Norg and Grijpskerk largely empty, meaning that the filling season started with storage facilities that were almost depleted.
Finally, we are constrained by several operational factors, such as the rate at which purchased gas can be injected into the different storage facilities. Injection rates vary by storage type and depend on technical characteristics, such as the number of compressors available. Recent warm weather has also played a role, reducing injection rates compared with normal conditions. Storage availability can additionally vary from day to day or week to week due to factors such as maintenance.
How do you view the role of market participants in this process?
Filling gas storage facilities is a joint effort. Market participants are largely responsible for meeting their obligations towards customers and covering delivery risks. In doing so, they also contribute to safeguarding security of gas supply. Particularly under current challenging conditions, it is important that they secure their supply obligations in a timely manner, either by storing gas or by entering into import contracts that provide for physical delivery.
What needs to happen in the short term?
As outlined, achieving the filling target depends on several factors. In the short term, the priority is to provide clarity regarding the future use of Grijpskerk.
How can underground storage facilities contribute even more effectively to security of gas supply in the future?
For many years, energy policy focused heavily on efficiency and confidence in global markets. Current geopolitical developments demonstrate that this approach is no longer sufficient. We must be prepared for structural uncertainty, greater price volatility and disruptions to gas supply.
This requires a reassessment of the role of gas storage facilities and the volumes required. At present, Bergermeer is the only storage facility that is commercially accessible, while the other facilities function primarily as seasonal storage. Available volumes, particularly low-calorific gas for households, may eventually exceed what is needed due to the expected decline in gas demand resulting from the energy transition.
To manage the risks associated with the current geopolitical situation, part of the underground storage capacity could be deployed as a strategic gas reserve, similar to the strategic oil reserves that are maintained today. This requires political decisions regarding risk coverage and scale. For example, should we cover half of gas imports for three months, or 75% for six months?
Establishing such reserves involves substantial costs, while the timing of their eventual use remains uncertain. This is generally unattractive for market participants and therefore constitutes a public responsibility. Any deployment of these reserves would occur in times of scarcity when gas prices are high, which is expected to offset a significant part of the costs.
So far, we have focused primarily on storage facilities. Looking ahead, what is the best way to safeguard security of gas supply?
First and foremost, the transition to a sustainable energy system remains the most important long-term investment in energy security. In the meantime, safeguarding security of gas supply remains essential. This requires an integrated approach that looks not only at storage, but also at domestic production and imports.
Significant gas potential remains available beneath the Dutch sector of the North Sea. To unlock this potential, a sector agreement was concluded last year. This strengthens cooperation between all parties involved, for example in the areas of data sharing and infrastructure. In practice, permitting procedures and available environmental space remain bottlenecks. By adopting a crisis approach to permitting, similar to the current approach for grid congestion, and by pursuing a more focused and less fragmented approach to nature development, the necessary acceleration can be achieved.
When it comes to imports, long-term contracts for physical gas delivery with a diverse range of suppliers can contribute to stability and security. Such arrangements remain uncommon in the Netherlands because commercial parties often find it difficult to carry the associated long-term risks. Yet these contracts provide certainty by guaranteeing that gas is physically available. Given the expectation that geopolitical tensions will persist, this is also a role that EBN could take on as part of its responsibility for safeguarding security of gas supply.